Short Guide to Buying Spanish property
Contents
Real estate market in Spain
Can foreigners buy property in Spain?
How will Brexit affect Spanish property buyers?
Why do foreigners buy property in Spain?
Who is the property buyer in Spain?
Searching for your dream property
Legal consultation
What to do before the transaction
How to avoid fraud and traps
Purchase process — two main stages
Mortgage
Additional costs and taxes
Costs when buying a home with a mortgage
After purchase: obtaining a Spanish visa
Conclusion: why use a real estate agent’s services — pros and cons
1. Real estate market in Spain

People buy Spanish property both for personal use and for investment. The yield on resort property is about 5% per year. In 2017, foreigners purchased 16% of all property sold in Spain. More than 14% of these foreigners were British.
2. Can foreigners buy property in Spain?
To purchase housing you will need to obtain NIE — a fiscal identification number, which is the primary document for non-residents of Spain.
NIE is the primary document for foreigners in Spain. Any foreigner has the right to buy Spanish property — you don’t need to be a resident for this.
The Spanish government supports foreign investment in real estate by providing a “golden visa” to those who spend more than €500,000 on purchasing one or more real estate objects. This type of investor visa allows residence in the country (but not work) and is popular among foreign retirees and vacation home owners.
3. How will Brexit affect Spanish property buyers?
Unfortunately, no one knows exactly what Brexit will change and how it will affect the market. According to general opinion, the British pound will continue to fall, so buying Spanish property will become more expensive for Britons.
Additionally, some fear for UK pension rights for those retiring abroad — they will no longer serve as proof of income. It will be necessary to confirm sufficient funds or invest €500,000 to obtain residency. Britain will likely conclude a bilateral agreement that will cover healthcare and resolve other emerging issues. It’s hard to believe that Spain will treat Britain — the main real estate investor — like other non-EU states.
Regarding mortgages, it’s believed that banks will not significantly raise rates after Brexit. However, it’s obvious that Britons will no longer enjoy the same rates as Spanish citizens. The main difficulties with mortgages will be related to risks of lending to those who receive salaries in an unstable currency.
Nevertheless, Britons have returned to buying homes in Spain after a year-long break following the Brexit vote. UK citizens are the main foreign investors in the Spanish real estate market, accounting for more than 14% of all foreign transactions.
According to the General Council of Notaries, UK investors completed 7,246 property acquisition deals in the second half of last year, representing 7.8% growth compared to the same period the previous year.
4. Why do foreigners buy property in Spain?
Owning a vacation home that can also be used by all family members as a place for joint holidays.
Investment purposes and rental income, which provides additional income during retirement.
Support for Spain’s stable economy, political situation, and real estate market development, which guarantees good resale potential.
Property prices are lower compared to pre-economic crisis standards and began rising again from 2014.
Cheaper flights in Europe. Spain has excellent infrastructure: international airports, high-speed trains, and the best roads in the EU.
Affordable prices for high-quality homes. Property prices are also lower compared to mortgage costs.
Ideal service at a good price. Cost of living is much lower than the EU average.
Variety of picturesque locations, for example, 47 UNESCO World Heritage sites, unique nature and warm seas, 320 sunny days per year, and the second longest coastline in Europe after Italy.
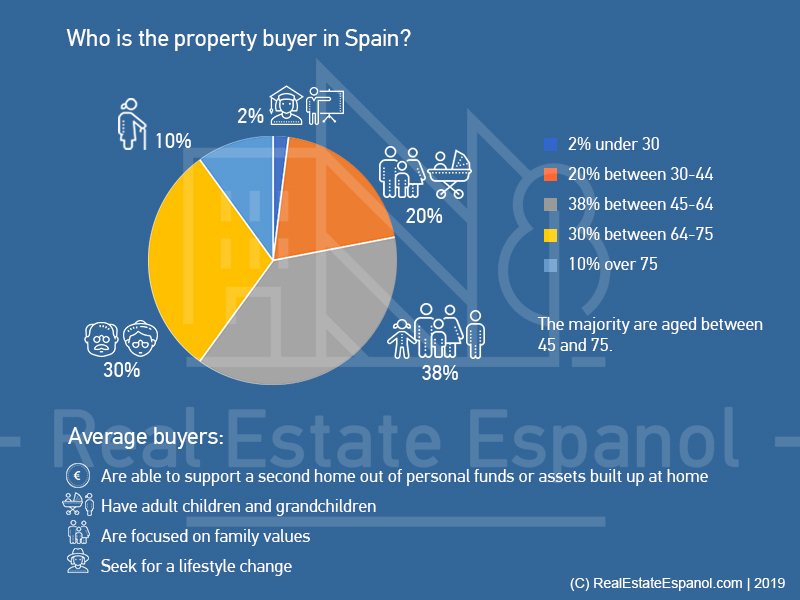
5. Who is the property buyer in Spain?
6. Searching for your dream property
Before diving into the Spanish real estate market, ask yourself several questions:
- “Why do I need a second home here?”
For clear understanding of this question, you need to define criteria by which you will choose your desired house or apartment on the Mediterranean coast. Remember: a house with a garden requires constant maintenance and additional costs. If you plan to spend only a couple of weeks per year in Spain, the best choice is an apartment in a gated residential complex, both for your budget and security.
- “How much does it cost?”
You need to carefully assess your needs and means before purchasing. Don’t forget about additional costs and taxes when buying and maintaining property. It’s also important to determine whether you’ll need credit. There are also additional expenses: mortgage processing, interest payments, and preparation of necessary documents.
- “Where is the property located?”
Location affects living comfort — whether it’s vacation, rental, or permanent residence. Proximity to the sea and walking distance to supermarkets, restaurants, and pharmacies are important when property is oriented toward tourists. If you plan to move to the Spanish coast, the priority may not be the beach, but a quiet residential area with a playground, park, bus stops, hospital, sports club, and school. But don’t worry — if the school is in another district, there are always school buses.
- “What to choose?”
You need to know the features of Spanish apartments, due to which demand is higher for properties on upper and lower floors.
Upper floor — often has a large terrace and private solarium with panoramic views, which can be used as a relaxation area with dining zone and barbecue.
Lower floor — often has an independent entrance or even a spacious courtyard with garden and parking.
Therefore, the cost of such properties is 20-30% higher than other apartments in the same building.
Common types of Spanish property are townhouses, bungalows (analogous to first-floor apartments), and villas. Consider the higher maintenance cost of property with a plot and/or pool.
7. Legal consultation
You will also need a team of specialists who will help successfully fulfill all necessary legal requirements:
Spanish notaries
A person authorized to certify Spanish documents, ensuring their compliance with certain legal criteria. The notary will convert your private purchase-sale contract into a public deed of sale (Escritura).
Real estate agent
When choosing an agent, you should pay attention to those who specialize in the local market. This allows the seller to be confident that when evaluating their property, not only the average market price will be considered, but also many other factors: neighborhood infrastructure, nearest municipal authority plans that may affect the property value, and so on.
Lawyer
The most important thing a lawyer (abogado, asesor) will do is make sure everything is in order with your chosen property. This is why it’s vital to find an independent specialist. The lawyer will check the owner’s documentation and their right to sell. They will ensure there are no debts, timely payment of community fees and annual property taxes by the current owner, and obtain other important information from the Land Registry.
Translator
You will need translation of all contracts for complete understanding of their content. Translation of some documents from your language to Spanish will also be required — for example, at the bank.
Currency specialist
It’s better to use a currency specialist’s services if you plan to transfer a large sum of money. They typically have significantly better exchange rates compared to Spanish banks. They are regulated by the FCA, so it’s a safe transaction. We recommend concluding a “forward contract” to know in advance the amount you’ll pay after purchase. We recommend finding such a specialist in your country.
Gestors
A Gestor is a consultant on general matters related to document flow, including real estate purchase and sale. One of their duties is document submission. Gestors specialize in various ways of obtaining official documentation or permits and understand client needs even if they don’t speak Spanish. For example, they can help resolve issues related to energy supply, local registration, tax payment, or opening an account at a Spanish bank. Gestor fees are lower than lawyer fees.
8. What to do before the transaction
- Get NIE — apply for NIE (Número de identificación de extranjeros), which is a personal tax identification number in Spain, mandatory for foreigners intending to buy property, cars, pay taxes, and even sign internet contracts or perform other legal actions.
It’s better to apply for NIE as soon as you start looking for property. You can obtain it in Spain or through a Spanish consulate in your country of residence.
Processing can take from one hour to 2 months for non-EU residents, so consider this.
Spanish bank account — open an account at a Spanish bank. When you know the amount and timing of transferring money from your account to the new Spanish one, it’s wise to notify the bank about this so the transfer isn’t blocked due to the large sum.
Insurance — when buying property with a mortgage, you’ll need property and life insurance. This is an official bank requirement, and this document can be processed at the same bank for convenience.
9. How to avoid fraud and traps
It used to be easy to encounter unscrupulous sellers and developers, but this problem has virtually disappeared.
Nevertheless, we strongly recommend making sure you don’t make a costly mistake.
First of all, check the documents of specialists you plan to work with, especially lawyers and real estate agents.
Check in the Land Registry:
Building permits;
Any debts encumbering the property;
“Comunidad de Propietarios” (community of owners) documents;
Property compliance with description and satisfaction with construction quality.
When buying new construction or under-construction property:
Make sure the chosen developer is officially registered;
Property registry, or “Registro de la propiedad”;
Check for urban planning permits;
Never sign a contract if you don’t fully understand every part of it;
Include a clause in the contract that you will receive a refund if the house is not built.
10. Purchase process — two main stages
The entire purchase process is divided into two main stages — preliminary contract and final deed (deed of sale).
After you find property, a reservation contract is concluded, fixing the purchase-sale price. Then within 10 days, contrato de arras is signed.
Stage 1: Preliminary contracts
New property (under construction)
“Contrato de Reserva” or “Contrato de Arras” is a type of option agreement. You’ll need to make a deposit of €3,000-15,000. Then you can apply for a mortgage if necessary. Decide whether it’s better to do this in your country or in Spain.
Secondary property
“Contrato de Arras” is a type of option agreement. You’ll need to make a deposit of €3,000-15,000.
When buying on the secondary market, you need to immediately sign “Contrato Privado de Compraventa” (preliminary contract). This contract expresses your intention to buy a specific property and removes it from sale. The deposit in this case is up to 10%. This amount will be held in an escrow account for a couple of months so you have time to check the chosen property. During this period, the purchase-sale contract will be drawn up and legal checks conducted. It’s important not to sign it without including provisions allowing exit from the contract.
Stage 2: Purchase-sale contract (Escritura)
Contact your bank and write a check in the name of the property owner or construction company (in case of mortgage) before visiting the notary.
This is the final stage when all parties meet at the notary’s. Your lawyer, mortgage lender (if necessary), and seller or their legal representative must be present. Before signing, make sure you clearly understand all expenses and have sufficient funds to pay all taxes and fees. Don’t forget to register ownership in the Land Registry.
Important note! To avoid traveling to Spain to sign all deeds, you can arrange power of attorney with a notary in your country.
11. Mortgage
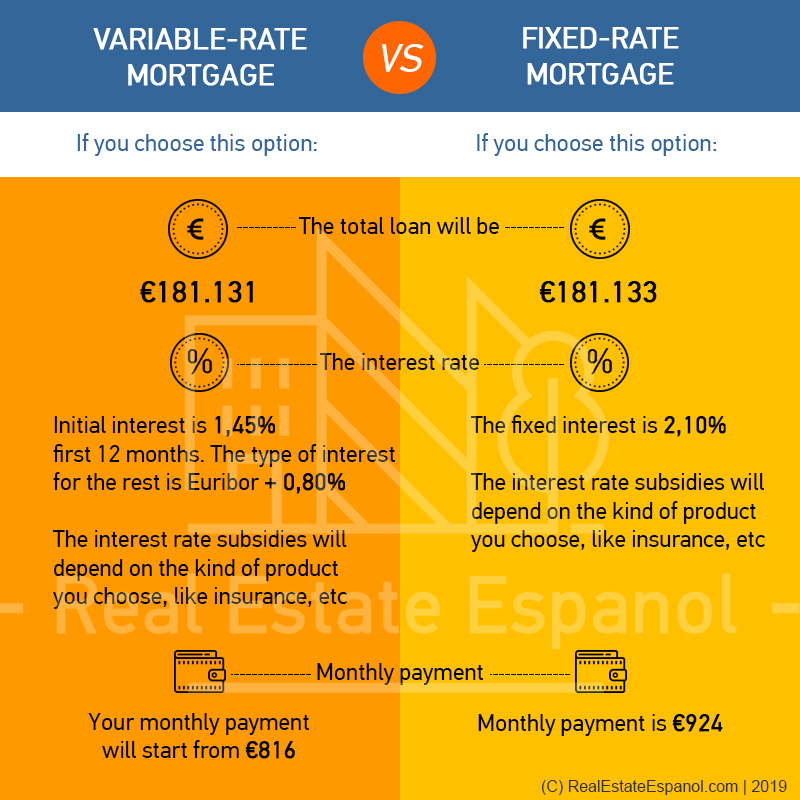
Variable rate mortgage from BBVA includes the following conditions:
No processing fees
Variable rate from Euribor +0.89 to Euribor +1.89 (depending on compliance with all or part of conditions: credit card use, housing insurance, salary transfer to account, etc.)
Variable annual percentage rate (APR) from 1.732%
First year: from 1.89% NIR (nominal rate)
Amount less than or equal to 80% of property appraisal value
Term up to 30 years
During the first year, the interest rate is fixed at 1.89% NIR. Then the interest rate starts from Euribor +0.89%. The specific differential depends on financing size, BBVA bank’s operation assessment, and acquired products.
Fixed rate mortgage from BBVA includes:
No processing fees
Fixed rate from 1.85% NIR for the first 6 months
Annual percentage rate (APR) 2.823%
The fixed mortgage rate depends on the chosen term (up to 15 years NIR 1.85%, from 26 to 30 years NIR 2.45%).
Kutxabank mortgage simulation
Let’s conduct mortgage modeling for this bank.
Suppose you are a 40-year-old UK citizen with a monthly income of €3,000-5,000.
You have saved €100,000 and plan to buy secondary property worth €250,000.
In total, you need to borrow €150,000. You decide to pay for 20 years.
What mortgage options are available to you?
12. Additional costs and taxes
Main taxes when buying in the primary market:
VAT (IVA) — 10% Stamp duty (AJD, IAJD) — 0.5-1.5%
When buying a house directly from a developer, you must pay 2 taxes. First, VAT (IVA) of 10% of the property value. Second, only new property buyers pay stamp duty, the size of which depends on the region and varies from 0.5% to 1.5%.
Main taxes when buying in the secondary market:
Property transfer tax (ITP) — 6-10%
The tax rate is set at the regional level and varies from 6 to 10%. For example, in Madrid — 6%, in the Canary Islands — 6.5%, in Andalusia, Valencia, Catalonia, and the Balearic Islands — up to 10%. ITP is paid to local tax authorities. In Madrid and Andalusia, payment can be made online.
Registry extract (Nota Simple) — €9
The registry extract contains information about the current property owner, type of object and its brief description (area in m², number of rooms, etc.). It also indicates existing debts and restrictions (for example, outstanding mortgage). The extract is requested at the property registry in person (ready the next day) or online (ready in 1-2 days).
Notarial services — 0.03-0.45%
The cost of notarial services depends on the price of the purchased housing. For example, for property in the price range from €60,101.61 to €1,552,503.03, the rate will be 0.1%. For cheaper properties, rates are higher; for more expensive ones, lower.
Registration fees — 0.02-0.175%
The registration fee is paid to the state and also depends on the property value. For the indicated range, it is 0.075%.
13. Costs when buying a home with a mortgage
Mortgage stamp duty (AJD, IAJD) — 0.1-2%
Charged when concluding a mortgage contract as a certain percentage of the loan amount according to the rate established in the region.
Property appraisal — €200-500 for average property
Independent appraisal allows the bank to determine if the housing price is inflated (in this case, the bank won’t be able to profitably sell it at market value if there are problems with the borrower). The more expensive the property, the more expensive its appraisal.
Notarial and registration fees
The cost of notarial processing and mortgage registration in the property registry directly depends on the loan amount.
Insurance — €300-350
Property insurance is mandatory; it’s often processed directly at the bank, which acts as an intermediary between client and insurer. Life insurance is also required in most cases.
14. After purchase: obtaining a Spanish visa
While Britain hasn’t left the EU, British citizens don’t need a visa to enter and reside in Spain. However, if you plan to stay more than 3 months, you must register at the Office for Foreigners, usually located at the Town Hall of your residence. You’ll receive a registration certificate, and your family members will receive a Union citizen family card.
15. Conclusion: why use a real estate agent’s services — pros and cons
Buying property abroad can be a complex process. There are many pitfalls that only professionals know about. It’s only worth doing everything yourself if you’re familiar with the entire process and know the region well.
Agent services are usually paid by sellers or developers. A commission of 5-10% is already included in the price. However, there are exceptions. Historically in Valencia and Malaga, a commission of about 3% for secondary market properties is not included in the stated price. Of course, the agency should warn you about this.
Remember that you can choose your lawyer, bank, and other specialists — you’re not obligated to use services offered by the agency.
Real estate agents often provide detailed information about the region and urbanization of the area where you’re considering a purchase. Most agents are bilingual and accustomed to working with foreign clients. Nevertheless, unscrupulous agents exist, so beware of those who ask for prepayment or offer to “cut corners.”