Spanish Mortgage for overseas property
Contents
Before submitting an application
Requirements for obtaining a mortgage as a non-resident
Process in brief
Documents for application submission
How much can I borrow?
Fixed or variable rate – what to choose?
Current mortgage rates in Spain – 2021
Costs and fees
Mortgage payment refunds
Refinancing and switching to another bank
What to remember when selling mortgaged property
Overpayment
Where to get a mortgage: in your own country or from a local bank
TOP Spanish banks
Conclusion
Key changes in Spanish mortgage legislation
Spanish mortgages after COVID-19
1. Before submitting an application
There are no restrictions for foreigners on purchasing real estate in Spain, but like any property acquisition process, obtaining a mortgage here has its peculiarities. Getting a mortgage is not difficult, however there are aspects that require special attention.
Make sure you meet the requirements
When providing credit, the bank considers certain mandatory requirements for the applicant. Before applying for a mortgage, make sure you fit the profile and that the bank won’t reject your offer. The requirements will be discussed further.
Prepare the necessary documentation
The bank will analyze all the information you provide, so it’s convenient to prepare all required documentation in advance. Additionally, it’s important to justify periods when you weren’t working or changed companies. You need to obtain a NIE in advance (about how to get a fiscal number, read here) and other necessary documents. A complete list of documents is provided below.
Calculate the exact amount
Before applying for a mortgage, you need to know the exact amount you need to pay for the chosen property. You should consider that purchasing housing involves additional costs such as property survey, notarial fees, and Land Registry registration fees. These additional costs will increase the total amount of the foreign property mortgage loan.
Pay attention to the fine print
When choosing a mortgage, you should carefully study the terms of the credit agreement. After signing, there’s no turning back. For this, you can use the help of a lawyer who can advise and warn about possible onerous conditions that you might not want to accept.
2. Requirements for obtaining a mortgage as a non-resident
Before calculating a mortgage, you should ask yourself several questions to understand whether you can apply, since banks usually don’t open doors to everyone when issuing loans — they always look for the ideal borrower profile to reduce risks.
Generally, banks have the following requirements:
Stable employment
It’s preferable to have at least six months of work experience at a specific company, and at least 2 years of continuous overall experience.
Income
When making a mortgage decision, the bank must ensure that the client doesn’t belong to a risk group for non-payment or loan payment delays. The possible financing volume and interest rate depend on income level. Monthly income should be at least three monthly loan payments (for example, if your payment is 400 euros, monthly income should be 1200 euros).
Savings
If the client doesn’t meet the requirement of having savings of at least 45% of the property value, they will have difficulties obtaining a mortgage (this includes mortgage processing costs and initial taxes, which amount to about 15%).
Credit history
The maximum requested loan amount can be increased with a positive credit history in Spain. That is, if a person has previously used banking financial services and had no problems with loan repayment.
Age
The ideal age range for obtaining a mortgage is from 25 to 60 years. If you’re over 65 and planning to buy property in Spain, we recommend allocating a share in the mortgage to younger family members with medium or high income, whose profile is more attractive to the bank.
3. Process in brief
A simple mortgage loan process includes 7 steps you need to go through:
Open an account at a Spanish bank
Open an account at a Spanish bank where you plan to arrange the mortgage.
Start the property appraisal procedure
Start the property appraisal procedure for the property you plan to purchase (no more than 2 weeks).
Prepare documents
Prepare and submit to the bank a package of documents for obtaining a mortgage loan.
Wait for the bank’s decision
Wait for the bank’s decision on the loan amount to be issued (usually no more than 60-70% of the property value).
In case of positive decision
In case of a positive decision, transfer the down payment to the bank account and cover additional costs associated with the purchase (taxes and others).
Sign the mortgage contract and deed of sale
Sign the mortgage contract and deed of sale (Escritura) in the presence of a notary. The original deed of sale is sent to the Property Registry, which verifies the legality of the transaction (takes from two to six months). If payment is made in installments, dates and payment amounts are specified in the contract. The document contains all information about the seller and buyer, plot and building characteristics, list of available equipment, etc.
Order a property ownership certificate — Nota Simple
After registration, you can order a property ownership certificate — Nota Simple, to claim a multi-visa or residence permit based on property ownership (from 500,000 euros). The latter information applies to non-EU residents.
We recommend applying for a mortgage after you’ve chosen a property and have a reservation contract in hand, as this is an important document the bank will request from you. Usually the bank reviews a mortgage application for a foreigner within two to five weeks.
4. Documents for application submission
General:
Passport/DNI
NIE (foreigner identification number)
Reservation contract (Contrato de arras/de reserva)
Marriage certificate, if the mortgage is for 2 people
Confirmation of any other income sources
Experian report (credit history)
Bank account statements for the last 6 months
Last mortgage statement, if applicable
Income confirmation:
For retirees: annual income confirmation
For employees: 3 latest pay stubs (paychecks), letter from employer, last tax return/P60
For self-employed: letter from accountant, tax returns for the last 2 years/SA302, audited statements for the last 2 years
All documents in languages other than Spanish or English must be translated into Spanish by a sworn translator. If the property is purchased in joint ownership, all documents must be provided by each future owner.
The bank welcomes any additional documents confirming the borrower’s financial solvency. These can be statements from private pension funds, investment funds, securities ownership certificates, etc. Remember: the more stable your economic position appears in the bank’s eyes, the more willingly it will provide the most favorable mortgage loan on your terms.
5. How much can I borrow?
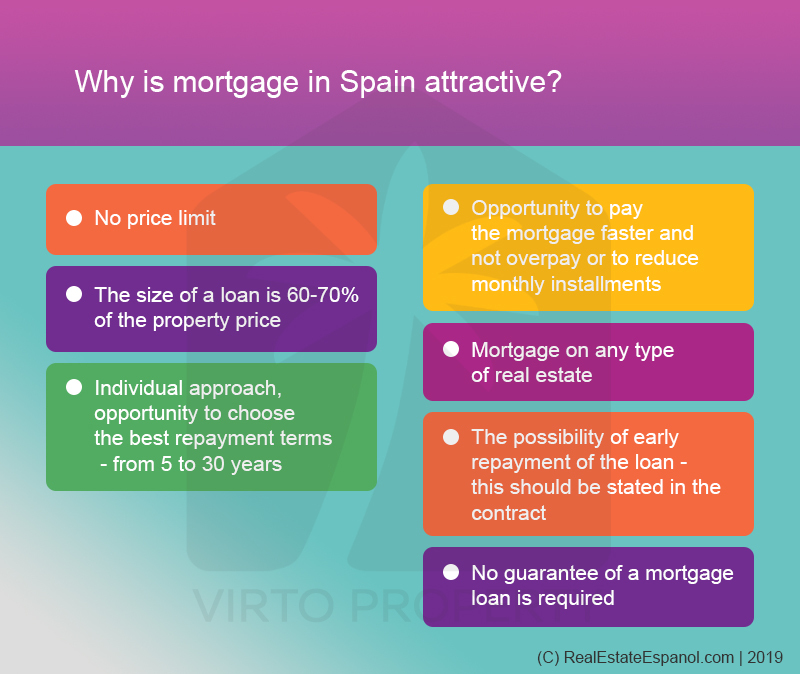
It should be noted that a citizen of another country buying Spanish property doesn’t need a guarantor to obtain a mortgage loan — and this is the main difference in the mortgage procedure between residents and non-residents of Spain. Despite this significant advantage, the maximum requested amount cannot exceed 70% (usually 50-60%) of the property value, while a Spanish citizen can claim 100% coverage from the bank. Your monthly payments should not exceed 35% of monthly income.
In practice, banks are more willing to issue loans for housing worth from 100,000 euros, as it’s more liquid than cheaper alternatives. The maximum amount is limited only by the borrower’s ability to confirm their income.
6. Fixed or variable rate – what to choose?

To determine the required mortgage amount, the buyer must know how much they can pay monthly, and not forget about interest rates that will apply to monthly payments. Mortgage rates are indeed lower than other types of financing, and the reason is that the housing itself serves as collateral for the bank.
Thus, if you stop paying the bank, it will take the house to somehow recover the money lent to you.
There are three types of mortgages depending on interest rate: mortgages with fixed, variable, and mixed rates.
Fixed rate
Fixed rate is ideal for those who prefer to know exactly how much they’ll have to pay each month. The lending organization offers an interest rate that doesn’t change throughout the entire payment period. In some sense, this provides security since the interest rate remains unchanged — throughout the entire mortgage term, the payment will be the same, as it doesn’t depend on index fluctuations such as Euribor. However, this type of mortgage tends to be more expensive since interest rates are higher — in this case, the bank takes on the risks of rate increases. 40% of borrowers choose this type of mortgage. The average rate for this type of mortgage is 3%.
Variable rate
Variable rate is the most common option in Spain. Its size is usually tied to Euribor, which must be considered when calculating a mortgage, since this index directly affects payments. They’re updated with each semi-annual review and will be higher or lower depending on fluctuations in the specified index. Currently, Euribor is at a historic low, and additionally, competition between banks has intensified, improving credit offer conditions. Currently, about 60% of all borrowers choose variable rate mortgages. The average rate for this type of mortgage is 2.45%.
Mixed rate
There’s also a mixed rate, though this type of mortgage is least common. As the name suggests, it combines the two previous options. The client will pay fixed payments for a certain period specified in the contract. Upon its completion, monthly payments become variable, according to Euribor.
What is Euribor?
Euribor is the interbank lending rate in the euro currency system, determined by the base rate (for main refinancing operations) set by the European Central Bank. The current Euribor rate can be checked here.
In simple terms, Euribor is the interest rate used to calculate mortgage payments in Europe. Euribor is used for both variable and fixed rate mortgages. When the base rate rises, Euribor follows it, and mortgage interest rates in the eurozone rise after it. The variable rate is determined by the formula: Euribor + X%.
When concluding a credit agreement, you should know: if the Euribor rate is negative (as currently), in the contract it’s equated to zero.
7. Current mortgage rates in Spain – 2021
So-called pricing is one of the most important elements distinguishing mortgages for residents from mortgages for non-residents, that is, the interest rate applied to borrowed capital and returned monthly.
Currently, mortgage rates are at the lowest level in history! As of December 2018, the number of mortgages issued in Spain increased by more than 20% compared to December 2017.
For foreigners
The average mortgage rate in Spain ranges from 2.44 (historic low in September 2020) to 3.5%, loans can be obtained for up to 30 years with the possibility of early repayment. The maximum that EU residents can count on is a loan of 70% of the property value. Foreign mortgages don’t require guarantees.
Residents
Spaniards must arrange loan guarantees but have the possibility to get 100% credit! In the case of non-residents, the rate is generally higher than for residents. The fixed rate is about 2.5% for 20 years.
Non-residents
For non-residents, the same rules apply as for foreigners, with one exception: the maximum loan amount is 60% of the property value for citizens of non-EU countries.
Requirements table
| Requirement | Value |
|---|---|
| Max. mortgage amount from property value | 70% |
| Min. mortgage amount | 50,000 EUR |
| Mortgage rates | 2.5% – 3.5% |
| Mortgage term | up to 30 years |
| Min. borrower age | 18 years |
| Max. borrower age at mortgage completion | 65 years |
| Max. monthly payments as % of monthly income | 35% |
8. Costs and fees
Taxes when obtaining a mortgage
Since November 2018, banks are required to cover all costs associated with mortgage processing, such as Gestoría, notary, Stamp Duty, and Registro, except for property appraisal. As of January 25, these costs were distributed between borrower and lender. Thus, the payment procedure is still being discussed, which creates confusion for international mortgage lenders.
Notary
Notarial fees are costs arising from processing the public mortgage deed. Notarial tariffs are established by regulatory acts approved by the government, and their amount depends on the mortgage obligation amount, though it may increase due to other factors such as number of copies, deed volume, etc. Notaries apply a fixed tariff, so each notary in Spain charges the same fee for the same service (they can provide a 10% discount). Competition between them is based only on quality. Usually the notarial fee is 1-2% of the property value.
Land Registry registration
The cost of registry registration depends on the mortgage amount. Registration fees must be added to the mortgage obligation amount. Usually this is about 500 euros.
Stamp Duty (AJD)
Stamp Duty is paid when signing any notarial document. The applicable tax rate is determined by each autonomous community and varies from 0.5% to 1.5%.
Transfer fees
You must pay property transfer tax (ITP) if you plan to buy housing or any other property on the secondary market. Depending on the autonomous community where the purchased property is located, a tax is applied that also depends on the object’s nature, its value, and some buyer characteristics (age, for example). The rate is 6-11% depending on each autonomous community’s tariffs.
Appraisal and processing fees (opening fee)
Appraisal: housing for which a mortgage is arranged will be appraised by the financial institution. This appraisal is mandatory by law and must be conducted by an organization registered with the Bank of Spain. It serves to determine the real market value of the property. The cost can range from 250 to 450 euros depending on the organization and final property value. The appraisal report is valid for 6 months from the date of issue.
Opening fee is usually from 0% to 2% of the loan amount (by agreement with the bank). The new regulation doesn’t prohibit charging this fee, though it establishes that this payment is charged only once and includes all costs for studying, processing, and providing credit or similar expenses.
Broker fees
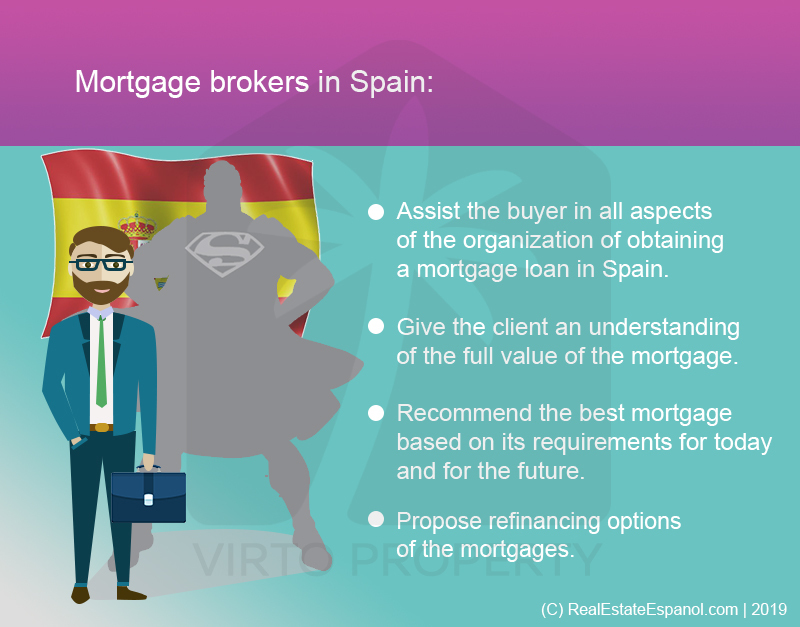
In Spain, there’s a huge variety of mortgage offers, each with its pros and cons, which requires considerable time and effort from the buyer to find the best option.
For many non-resident buyers, the best solution might be turning to a mortgage broker specializing in Spanish mortgages for foreign property.
A good Spanish mortgage broker can be of great benefit, but if the buyer has good credit history and can devote time to analyzing Spanish mortgage conditions, a foreign mortgage broker might not be necessary. Direct application to lending institutions allows saving the broker’s commission of 0.5%–1% of the credit value.
Insurance
Home insurance is one of the most common additional expense items when paying a mortgage. The law requires that mortgaged housing be insured. This will cost you 250-350 euros per year.
Banks usually try to sell their own insurance when arranging a mortgage and will likely offer better conditions if the client purchases several products simultaneously, such as home insurance or life insurance. It’s important to note that life insurance is also mandatory for mortgages — usually it’s arranged once when obtaining credit.
Early repayment
Since banks lose profit from early loan repayment, a penalty is provided. According to the new law in effect since 2018, the fee was reduced and amounts to:
In case of variable rate mortgages, the early repayment fee is 0.5% of the amount paid early if payment occurs in the first 3 years of the mortgage contract, 0.25% — from 3 to 5 years, and free after 5 years of the contract;
In case of fixed rate mortgages, the early repayment penalty is 4% of the amount paid early in the first 10 years. After this period, the borrower pays a 3% fee.
The fee is calculated from the amount of money paid early, for both fixed and variable rates.
Partial repayment
When arranging a mortgage, you usually repay the loan with monthly payments. However, if you have additional funds, you can pay the bank more than usual. This early repayment is called “early repayment” and can be of two types: partial mortgage repayment — if you return only part of the debt amount to the bank; or full repayment — if you pay off the entire remaining debt.
Some organizations apply a partial repayment fee, which currently cannot exceed the following limits: 0.5% during the first five years of the mortgage and 0.25% thereafter.
Subrogation
There are two types of subrogation:
Debtor subrogation
Creditor subrogation
If you want to buy property with an attached mortgage, there’s good news for you: costs for debtor subrogation (transferring the mortgage to another owner) were reduced since 2018. Banks charge a 0.25% fee for changes made before the third year of the mortgage; the fee after 3 years equals zero. Additionally, in this case you’ll have to pay a notarial fee of 30 euros and registration fee — 24 euros.
If subrogation is possible, consider: debtor subrogation means you’re ready to accept current mortgage conditions — loan term and interest rate, which may not be the best compared to other banks. Creditor subrogation will be discussed further.
9. Mortgage payment refunds
On December 23, 2015, the Supreme Court issued a ruling recognizing the practice of imposing all costs on the borrower as unfair. Currently, only those who signed a mortgage loan (or will sign) between December 2011 and December 2019 have the right to demand a refund.
According to the Supreme Court decision, the following costs should not have been imposed on borrowers:
Notarial fees
Usually amount to 0.1% to 0.5% of the mortgage obligation amount. The borrower can recover half the paid amount.
Gestoría
The amount to pay is not regulated by law. Usually about 400 euros. The borrower can also get 50% of the paid amount.
Property registration costs
Usually don’t exceed 0.2%. The borrower can demand full refund.
Regarding property appraisal costs, the borrower can recover them if there was a valid appraisal before mortgage processing (performed by an accredited company), but the bank rejected it and forced the borrower to hire another agency’s services for re-appraisal. In this case, the borrower can file a regular claim with the bank or go to court specializing in unfair conditions.
Let’s consider the steps to take for quickest money recovery:
Collect all service bills paid after contract processing
These are bills you received several weeks or months after signing the mortgage loan. Having all this documentation will give you grounds for demanding the bank refund a certain amount.
File a claim with the bank’s customer service
The bank must respond to you within one month.
You can file a complaint with the Bank of Spain
If the bank didn’t respond or rejected your request. The Bank of Spain will issue a conclusion on your situation within a maximum of four months — though it won’t be binding, you can use it for a repeated claim.
Finally, if the bank still doesn’t accept your demands, there’s always the possibility of filing a lawsuit
Of course, you should evaluate all pros and cons of litigation, since victory isn’t guaranteed, and in case of loss you’ll have to cover all costs associated with the process. On the other hand, if you win, the bank will be obliged to pay all court costs and return money according to the court decision.
10. Refinancing and switching to another bank
Refinancing is changing the basic conditions of your mortgage. It can include loan amount, repayment term, interest rate, and payment schemes.
Reasons for refinancing vary, including the need to increase loan amount and reduce monthly payments.
There are two main ways to refinance in Spain:
Creditor subrogation
Cancellation and reopening
The most effective way to improve mortgage conditions is usually reducing the interest rate. The cost of such renewal includes notarial costs and registration fee, as well as penalty from the previous bank of 0.25% (currently) and opening fee for the mortgage at the new bank.
Banks usually offer special promotions to attract new clients, inviting them to reprocess existing credit without associated costs. At the same time, it’s important to carefully study conditions to avoid falling for marketing tricks.
The second refinancing option — cancellation and reopening — is more expensive since it includes mortgage cancellation fee (usually about 0.5% of credit balance), registration fee for cancellation, new mortgage opening fee, notarial costs, and registration fee for opening a new one.
11. What to remember when selling mortgaged property
The first thing to know when selling mortgaged property is how much money you spent on the property, what the mortgage balance is, and what amount you can get from the sale.
Thus, you can choose the optimal option: mortgage repayment, subrogation, or bridge mortgage.
Mortgage repayment
To conduct mortgage repayment procedure and get money in case of selling an apartment at a price above the remaining debt, you need to request a debt certificate from the bank. Then, after signing documents with the notary, the buyer is obliged to register debt repayment in the registry.
Sale below debt value
If you sold an apartment below the residual mortgage payment value, even if you direct all money from the sale to the bank for mortgage repayment, you’ll have unpaid debt to the bank. Of course, this new debt doesn’t mean you still have mortgage debt. It’s simply a new loan, so you should calculate in advance to understand whether it’s worth selling the property now.
Subrogation when selling
When selling mortgaged property with subrogation, usually the seller continues paying the mortgage, and the buyer becomes the seller’s debtor for the property purchase. Thus, in case of buyer default, the seller may face two lawsuits: against the buyer for subrogation non-performance and against the bank, which will demand mortgage payment.
12. Overpayment
To determine when it’s better to overpay on a mortgage, you need to consider not only your financial situation but also market situation, primarily the Euribor value.
When overpaying, you need to choose between reducing payment or shortening the term, considering that interest savings are greater when shortening the term.
In principle, when the payable interest is very low, as now, with negative Euribor since 2016, early mortgage repayment doesn’t make much sense since the savings you can get are lower than with high interest rates.
From a financial standpoint, it’s unprofitable, but it might be interesting if you have the right to tax deduction. If you signed a mortgage before January 2013, you can deduct up to 15% of contributions made during the year in your tax return, with a limit of €9040 or €18080 with two owners filing separate returns. The maximum savings from tax deduction is €1356. In these cases, it’s important to overpay to achieve the maximum possible deduction amount.
So, to understand whether it’s worth overpaying on a mortgage, it’s best to perform the following calculations considering early repayment fees described above:
Overpayment comparison table
| Parameter | Variable rate mortgage | Fixed rate mortgage |
|---|---|---|
| Total amount | 150,000 € | 150,000 € |
| Term | 20 years | 20 years |
| Interest rate | Euribor + 0.99% | 1.99% |
| Interest payable | 12,481 € | 28,687 € |
| Payment | 677 € | 744 € |
| Early repayment | 40,000 € | 40,000 € |
| Early repayment fee | (0.5%) 200 € | (4%) 1,600 € |
| Early repayment fee | (0.25%) 100 € | (3%) 1,200 € |
| Interest savings with payment reduction | 3,344 € | 8,564 € |
| Interest payable with term shortening | 5,986 € | 16,102 € |
From this simulation, it’s clear that the higher the payable interest, the greater the interest savings from early mortgage repayment. Considering that in the first years you pay more interest, it’s more beneficial to make amortizations precisely in these years, but while calculating whether the savings compensate for fees, which are higher in the first years. However, from the sixth year onward, no fee is charged.
Nevertheless, you should also evaluate: if the interest paid on the mortgage is lower than what can be obtained from investments, then overpaying is inadvisable. In conclusion, remember that for early mortgage repayment you need to evaluate the applicable fee and whether it compensates for interest savings.
Important warning
YOUR HOUSING CAN BE SEIZED IF YOU DON’T MAKE TIMELY MORTGAGE PAYMENTS.
This means that if you don’t pay your mortgage on time, the bank can take your property since a mortgage is a loan secured by the purchased property.
13. Where to get a mortgage: in your own country or from a local bank
There are several reasons to choose a mortgage in Spain compared to a mortgage in your own country.
First, considering exchange rate fluctuations, it’s better for property and mortgage to be in the same currency — this reduces overpayment risk and prevents other currency inconveniences. A mortgage in foreign currency isn’t the best choice for this reason.
Second, it makes sense to have monthly mortgage payments in the same currency as rental income if you plan to rent the property and use the income for mortgage repayment.
Currently, mortgage rates in Spain are among the five lowest in Europe, and this indicator will likely persist in the foreseeable future. This means monthly payments will likely be smaller with a Spanish mortgage compared to any other country.
On the other hand, the cost of opening a mortgage in Spain can be quite high considering notary, registry, taxes, and other organizational costs. But considering the latest court decision, these costs are shared between borrower and lender, so now this can be beneficial.
Buy to let mortgage
How does a buy to let mortgage work? Rental property must pay for itself, that is, the mortgage loan is paid through rental income. The minimum down payment for a Buy to let mortgage is about 20-25%. Banks consider buying property for rental more risky than buying your own home.
Can I get a Buy to let mortgage? Unfortunately, it’s impossible to get such credit from Spanish banks. But in some exceptional cases, experienced investors might be offered this type of mortgage.
14. TOP Spanish banks
There are Spanish banks that see prospects in providing mortgages to foreigners and create teams specializing in this type of client, including consulting services, guaranteeing the notarial process and Land Registry registration.
Among the most active in providing mortgages to foreigners are Santander, Ibercaja, Bankinter, Hipotecas.com, Abanca, and Bankia. Some have specialized services for foreign operations, others bet on this niche thanks to strong presence abroad or on the Spanish coast, where most transactions take place. For example, Santander has strong presence in the UK, Portugal, Poland, Mexico, Brazil, Chile, and Argentina, while Bankia strengthened presence in the Mediterranean region after integration with BMN bank.
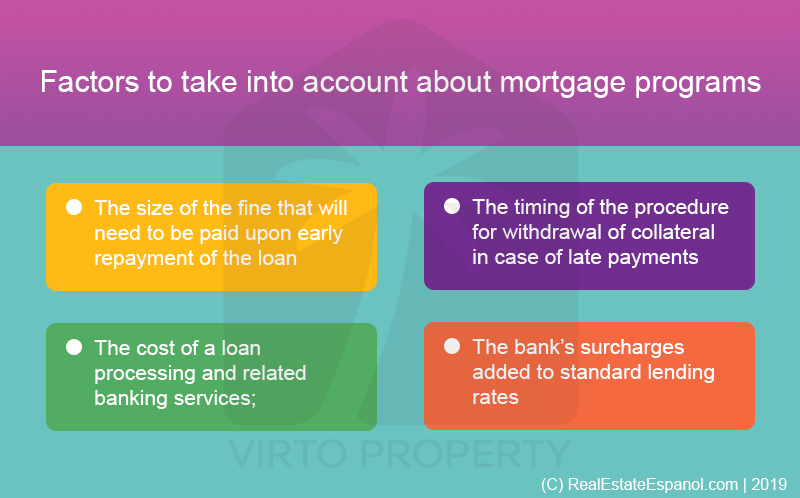
Most banks in Spain are ready to offer a wide range of mortgage programs combined with an individual approach to clients. However, when making a decision, several factors should be considered.
According to Registradores, the coast and islands are regions with the highest number of purchases, since housing is usually acquired as a second vacation home. The most frequent buyers are British, French, Germans, Belgians, and Swedes, and the most demanded provinces in 2017 were Alicante, Tenerife, Balearic Islands, Girona, and Malaga. In all of them, foreigners make up more than 30% of mortgage borrowers.
The best way out in such a situation is to visit several banks to compare offered mortgage conditions for non-residents and choose the most suitable ones. For complete analysis, parameters such as loan size, terms, rates, insurance, additional services and their cost should be considered. When conducting analysis, it’s recommended to use mortgage calculators available at all banks. This will allow calculating payment amounts depending on mortgage program conditions.
Variable rate mortgage trend
Variable rate mortgages are an attractive option for those looking for 10-20 year loans. Now is a good time for variable rates since Euribor has been close to negative values for the 4th consecutive year. Financial institutions don’t prioritize such loans since their current profitability is low, so recently their main focus has been fixed mortgages. Nevertheless, variable rates can be a good choice for those who now aim to pay a small monthly payment.
Freedom mortgage from Banco Mediolanum offers financing up to 80% of property value for up to 30 years. With fixed rate 1.99% TIN in the first year and Euribor + 1.10% from the second year + variable APR 1.28%. With a 150,000 EUR loan, monthly payment is 484 EUR.
Sabadell also offers an attractive option: first year TIN of a 30-year mortgage is 2.15%, and after that — 1.35%. With a 150,000 euro mortgage for 30 years, monthly payment will be about 536 EUR.
For its part, Coinc offers an interest rate of 1.89% in the first year and 1.10% in the second with APR 2.14%. Monthly payment — 545 EUR.
ING has created several variable rate mortgage options. On one hand, when arranging a mortgage with direct salary debit and home and life insurance offered by the bank, rates are: APR 2.65%, 1.99% TIN in the first year, then Euribor + 0.99%. Without purchasing the listed products, TIN after the first year will be Euribor + 1.79%. The maximum term for this mortgage is 40 years. If the client chooses this loan for 150,000 euro housing, monthly payment will be 584 euros.
15. Conclusion
Spanish mortgage in numbers
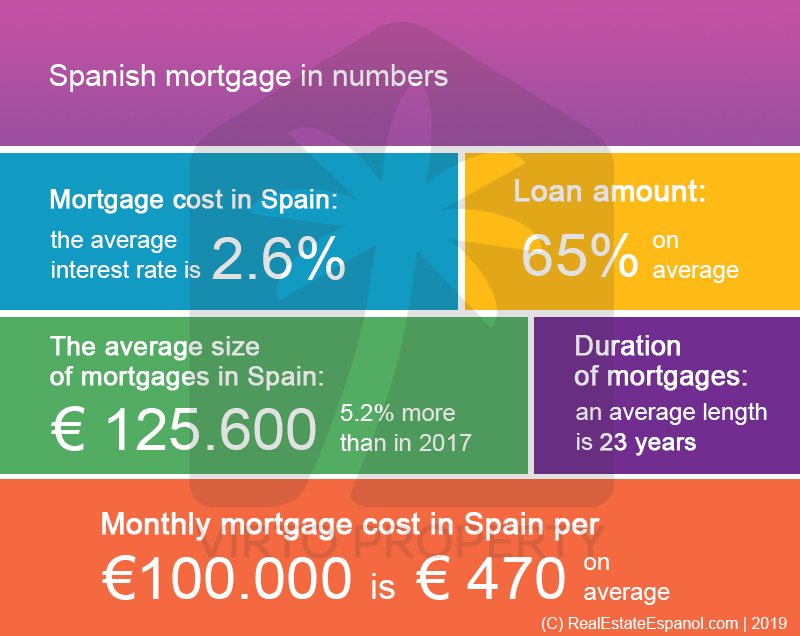
We recommend starting to study the mortgage market as early as possible for the following reasons:
The bank may need up to a month to decide on providing credit if additional documents and income confirmation are required.
You should analyze all pros and cons and decide how much to borrow and where it’s better to do this — both regarding country and bank.
Understanding Spanish mortgage features will reduce the risk of losing your dream property that you’ve been searching for so long if you have to make decisions and wait for bureaucratic procedures for months.
Overall, Spanish banks are loyal to various clients. Some are more favorable to UK citizens, others to Ukrainian citizens, etc. This depends on the region where you plan to arrange the mortgage, as well as the specific branch. Your real estate agent should help with bank selection, considering current international mortgage programs.
16. Key changes in Spanish mortgage legislation
Changes in cost distribution when arranging mortgages
Now the bank covers:
notarial fees;
own copy of notarial deed;
property registrar services;
tax on documented legal acts (AJD);
consulting company services (gestoría).
Client covers:
own copy of notarial deed;
property appraisal.
Early mortgage repayment fee reduced
For fixed rate mortgages, maximum fee:
2% during the first 10 years;
1.5% after 10 years.
For variable rate mortgages:
0.25% during the first 3 years of the contract;
0.15% during the first 5 years.
After this period, the fee is 0%.
Transition to fixed rate simplified
If the bank where you have your mortgage offers similar or more favorable conditions, you’re no longer obliged to accept them.
Bank switching procedure became freer
Maximum switching fee is now 0.15%, and it’s charged only in the first 3 years.
Property seizure requirements became stricter
Banks can terminate contracts early to file property seizure lawsuits under the following conditions:
In the first half of the loan term:
Non-payment amount exceeds 3% of the provided amount;
Amount equals 12 unpaid installments.
In the second half:
Non-payment amount exceeds 7% of the provided amount;
Amount equals 15 unpaid installments.
Maximum interest rate for payment delay can exceed the mortgage rate by no more than 3 points.
Banks prohibited from forcing clients to buy their financial products
Now banks cannot force clients to contract home or health insurance, etc. when arranging mortgages. But they can offer more favorable mortgage conditions when contracting several services simultaneously.
Banks can also require home or life insurance. But you’re not obliged to do this at the bank issuing the mortgage. Now for all mortgage loans, the minimum rate is 0%.
Banks required to provide client with 2 documents
FEIN — European Standardized Information Sheet, which will allow comparing the offered credit with others on the European market;
FiAE — standardized warning card presenting main risks and expected cost scenarios.
Credit recipient required to consult with notary before signing contract
The borrower is required to consult with a notary within 10 days before signing the contract.
During this consultation, test questions must also be answered; without this procedure, no notary will be able to certify your contract.
All contract provisions contradicting the new law will be declared invalid, and there will be no statute of limitations for filing complaints. A new judicial body will be created to consider claims and complaints about mortgage loans.
For those who got mortgages in foreign currency, conversion to euros will be possible at any time. The bank is obliged to notify the client about debt increase due to currency rate growth relative to the euro.
17. Spanish mortgages after COVID-19
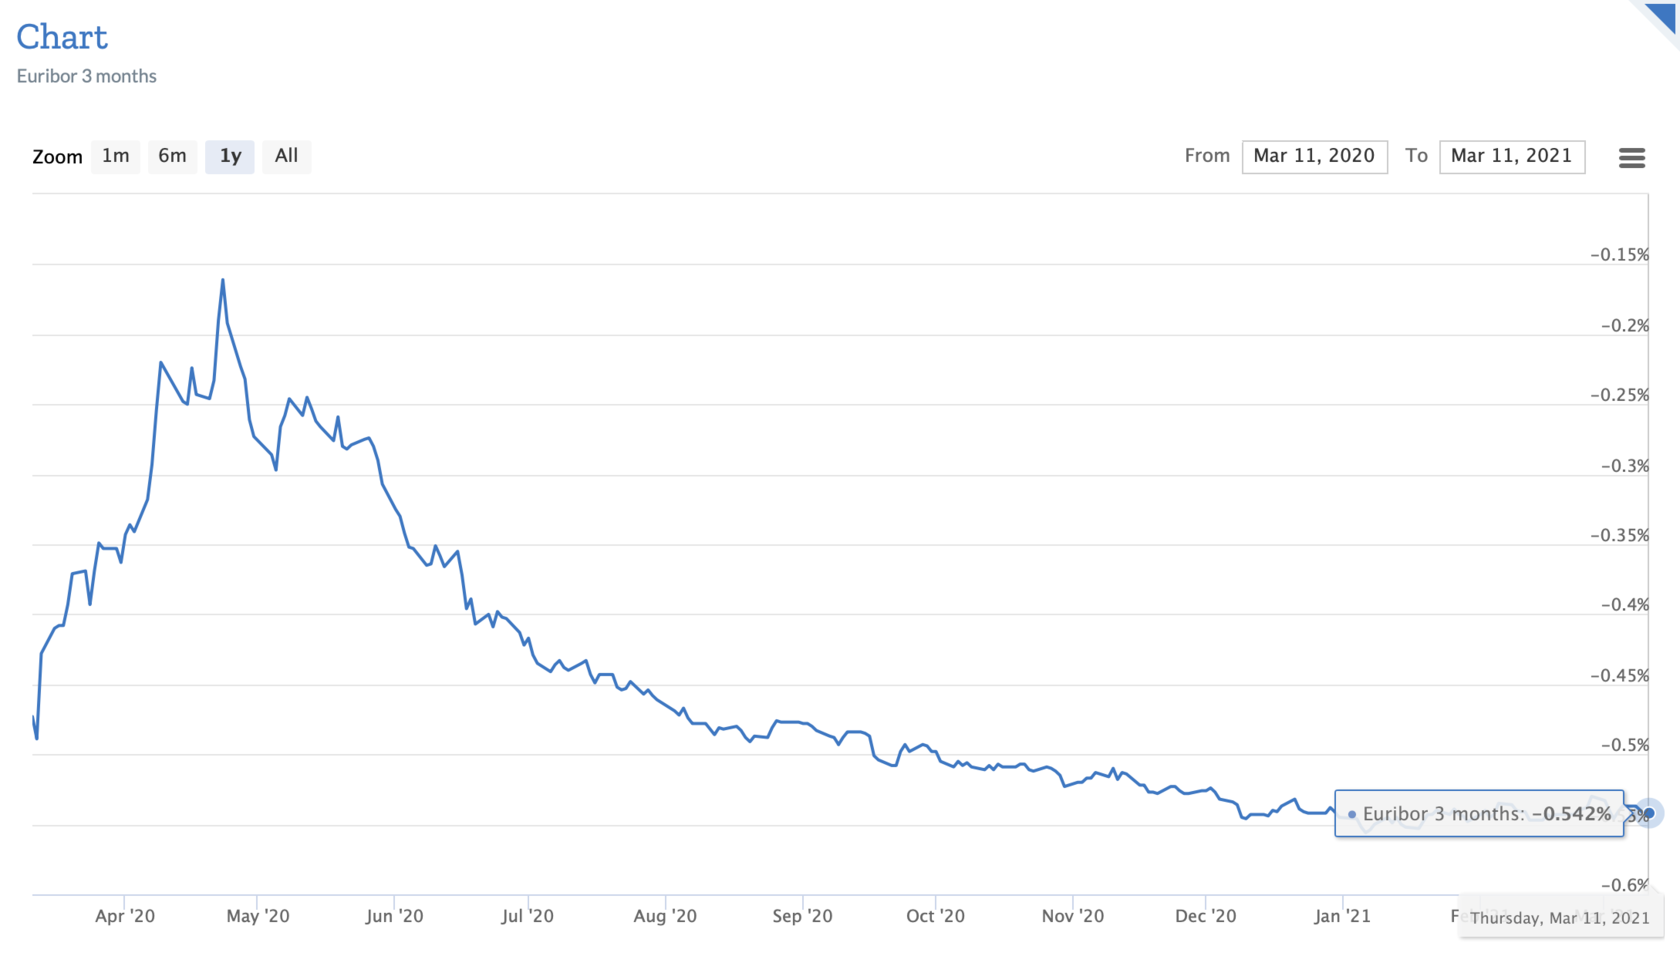
New housing loan issuance noticeably recovered after the COVID-19 outbreak in March–June 2020, but not enough to compensate for coronavirus losses.
In 2020, more than 251,000 new mortgage loans were issued, and the year ended with 2.7% more loans in December compared to December 2019. But this happened thanks to sector recovery in the second half of 2020. In summary, the Spanish mortgage market ended the year with a 7.6% loss in volumes, returning to 2017 levels.
The average cost of a new housing loan in December 2020 was €147,600, approximately 5% more compared to December 2019.
Since Euribor reached a historic low in 22 years, variable rate mortgages became more profitable. Variable rate payments decrease by several hundred euros per year (depending on loan amount). Experts link the indicator decrease to the European Central Bank’s monetary stimulus policy due to pandemic consequences, aimed at easing tension in the banking sector.
In the economically difficult context similar to what covid left, experts believe banks may tighten mortgage criteria and become more selective. This is especially relevant for second homes or residential property — a niche representing greater risk for banks.
Currently, banks are particularly demanding in providing mortgages to non-residents with currencies other than the euro — this is related to the new mortgage law allowing clients to change payment currency at any time. This situation creates difficulties for banks since it involves accepting significant risk due to currency fluctuations, leading many banks to limit mortgage issuance.
But in practice, residents of the European Union, UK, Scandinavian countries, and USA have higher chances of getting loans thanks to stable economy and favorable monetary policy. If someone is from another country, everything depends on agreements between that country and Spain.
Nevertheless, many non-residents from the listed countries successfully obtain mortgages. How can this be done? The most effective way is to engage a mortgage broker. A specialist will evaluate the applicant’s profile and contact banks that work best with this type of client.
Possibility of preliminary approval
You can get preliminary mortgage approval without leaving your country.
Negotiations with the bank will be conducted by Virto Property managers before your arrival in Spain. Any Spanish bank will request passport/ID copy, tax return, and credit history.
Thus, preliminary credit approval can be obtained while in your country, before signing the transaction.